
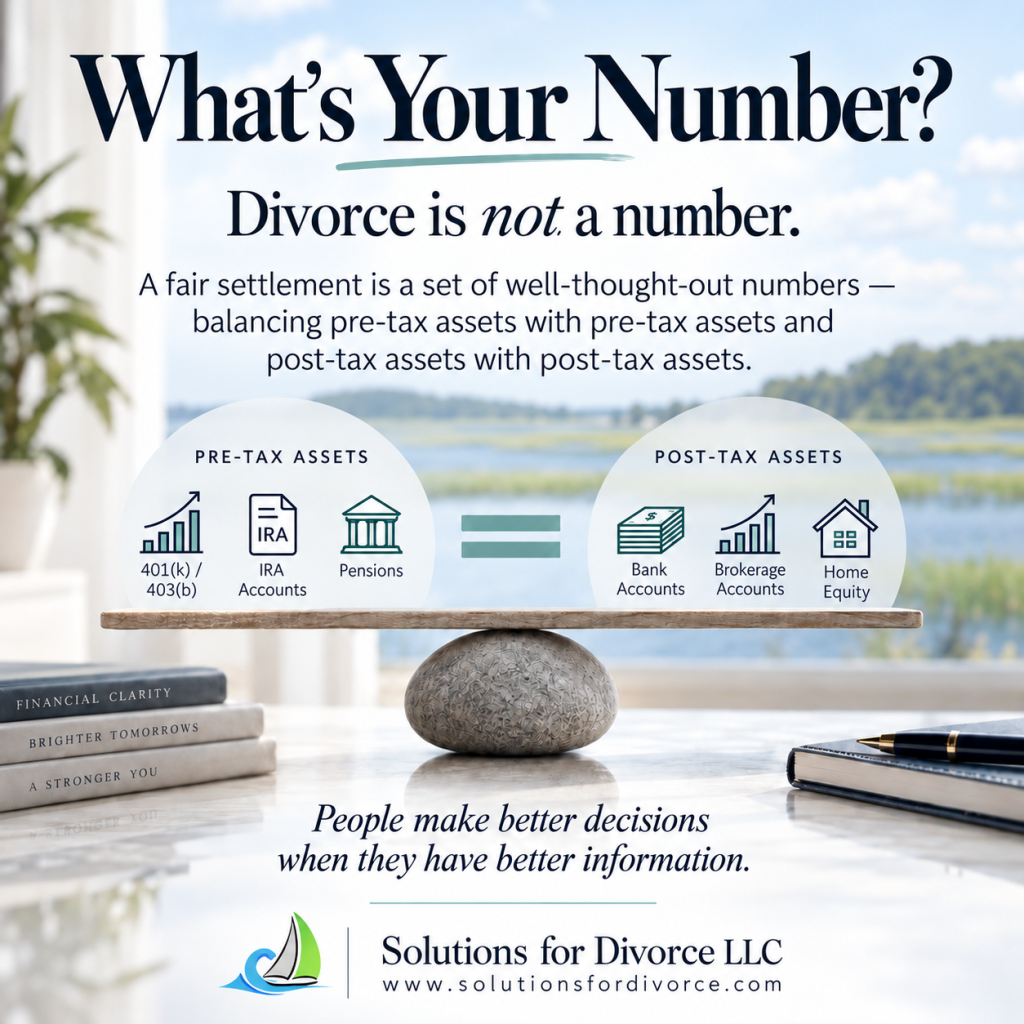
“What’s your number?”
That was the question a retired judge, now working as a divorce mediator, recently asked one of my clients.
My first thought was, What does that even mean?
Divorce is not a number.
A divorce financial settlement is not simply about agreeing on a dollar amount. It’s a carefully thought-out agreement that addresses the unique needs, concerns, and goals of both parties. It requires an understanding of not only what the parties own and owe today, but also how the decisions they make during the divorce will affect their financial lives tomorrow and well into the future.
Reducing a divorce settlement to one number oversimplifies what can be one of the most significant financial decisions a person will ever make.
Not All Dollars Are Created Equal
One of the most important concepts I explain to my clients is that $100,000 in a retirement account is not the same as $100,000 in a savings account.
Retirement accounts generally contain pre-tax dollars, meaning income taxes will eventually be owed when those funds are withdrawn. Savings accounts, on the other hand, generally contain post-tax dollars that can be accessed without an additional income tax liability on the principal.
And what about the marital home? A house may have significant equity, but that equity isn’t necessarily available to pay the mortgage, buy groceries, or cover everyday living expenses. There are also ongoing maintenance costs, property taxes, insurance, and potentially capital gains taxes to consider.
So, when someone asks, “What’s your number?” my response is that there shouldn’t be just one number.
There should be a set of numbers that reflects the different types of assets, their tax treatment, their liquidity, and their ability to support each party’s financial future.
Whenever possible, pre-tax assets should be equalized with other pre-tax assets, and post-tax assets with other post-tax assets. When unlike assets are exchanged, the financial consequences of that exchange need to be understood and evaluated.
Otherwise, a settlement that looks equal on paper may be anything but equal in practice.
Equal on Paper Doesn’t Mean Equal in Life
Consider two people who agree to divide their marital estate equally.
One keeps the house. The other keeps the retirement accounts.
The values may be identical on the financial statement, but what happens next?
Can the person keeping the house afford the mortgage, taxes, insurance, and maintenance on their income alone? Will they have sufficient liquid assets to cover unexpected expenses?
And what about the person keeping the retirement accounts? How much of that money will actually be available after taxes? Will they have sufficient cash to purchase another home or cover living expenses without making taxable withdrawals?
These are not minor details. They are fundamental questions that should be answered before a financial settlement is reached, not after the divorce is final.
This Is Where a CDFA Makes a Difference
As a Certified Divorce Financial Analyst® (CDFA®), my job isn’t simply to add up the assets, subtract the liabilities, and divide the difference by two.
My job is to help clients understand the financial consequences of their decisions.
That means analyzing different settlement proposals, evaluating cash flow, considering tax consequences, reviewing retirement benefits, and determining whether the proposed division of assets will allow each party to meet their financial needs.
Sometimes, what a client initially thinks they want isn’t necessarily what will serve them best financially.
A client may be determined to keep the marital home, only to discover through financial analysis that doing so could leave them house-rich and cash-poor.
Another may believe that receiving a larger share of the retirement accounts is a better deal, without realizing how much of those funds may eventually be lost to income taxes.
The purpose of financial analysis isn’t to tell people what decisions to make. It’s to give them the information they need to make those decisions with confidence and clarity.
A Settlement Should Be More Than a Negotiated Number
Mediation is about helping people reach agreements. But an agreement is only as good as the information used to make it.
When the conversation begins and ends with “What’s your number?” we risk overlooking the very things that make each family’s financial circumstances unique.
How much income will each person need after divorce? What assets will be available to generate that income? What are the short-term and long-term tax consequences? What happens when someone retires? What financial risks is each person assuming?
These questions matter.
And they cannot be answered by simply choosing a number and negotiating until both parties agree.
The Three Questions I Want Every Client to Answer
Throughout the divorce process, I encourage my clients to think about three things:
- Where am I financially today?
- What will my financial situation look like the day after my divorce?
- What will my financial future look like five, ten, or twenty years from now?
A well-designed divorce settlement should consider all three.
There may ultimately be a number—or several numbers—that the parties agree upon. But those numbers should be the result of thoughtful financial analysis, not the starting point of a negotiation.
Because the goal isn’t simply to reach an agreement.
The goal is to reach an informed agreement that works for the people who will have to live with it.
I have always believed that people make better decisions when they have better information.
And when it comes to divorce, that information is worth far more than any single number.
